(630)-286-9465
+123 (4567) 890

Best Property Insurance Appraisal Services Built for Pricing Disputes

A roof claim can stall when two estimates refuse to meet. Appraisal offers a faster path than court, and Claim Guard powers property insurance appraisal services with Xactimate files that stand up to every question.

Roofers, contractors, and public adjusters use our insurance appraisal service to get appraisal-ready Xactimate estimates, supplements, and umpire support. You upload the carrier’s numbers, photos, and measurements, and the file returns in 48 hours.

Book A Call

Giant Hail, Costlier Roofs, and the Reasons Chicago Area Claims Stall

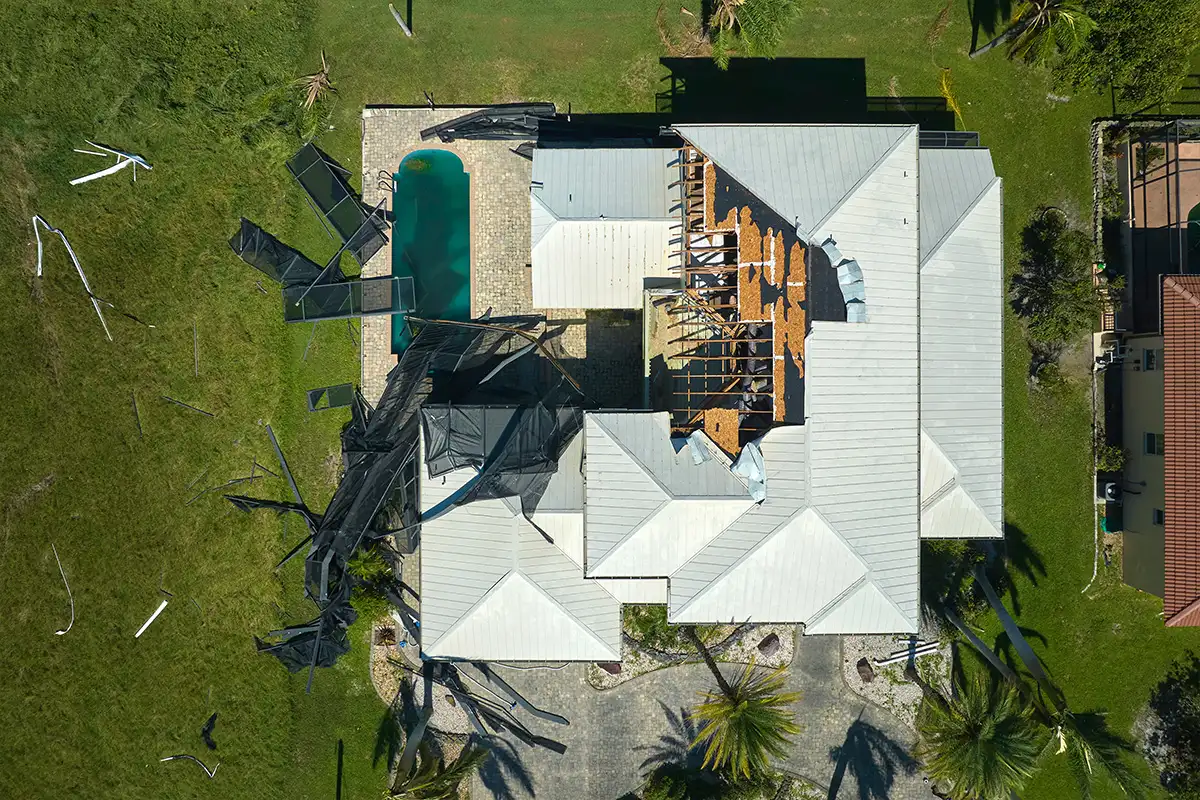
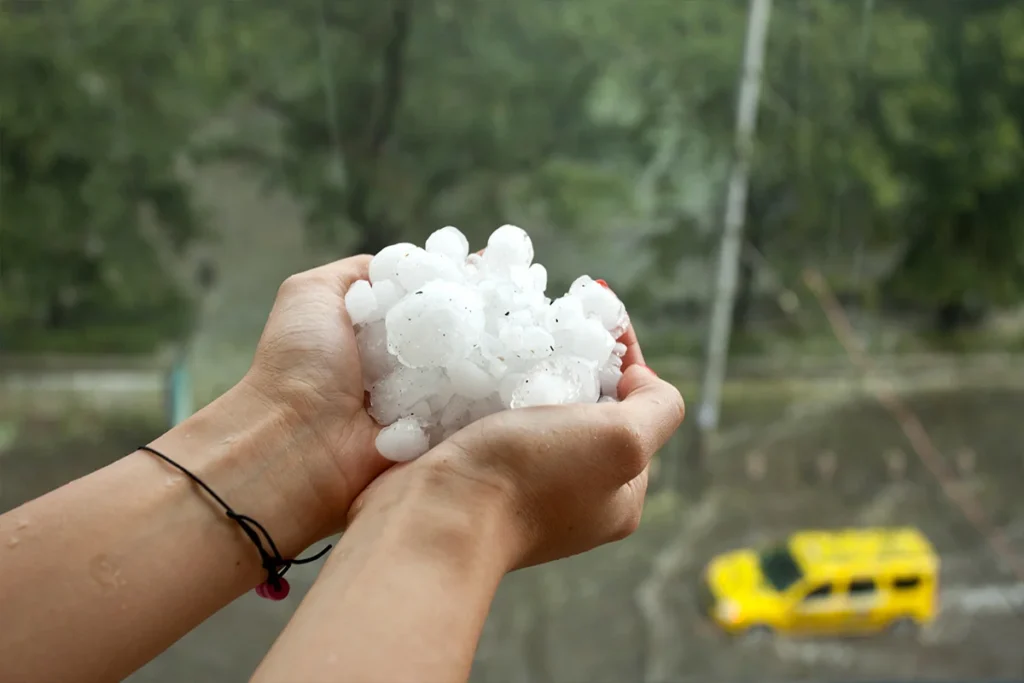
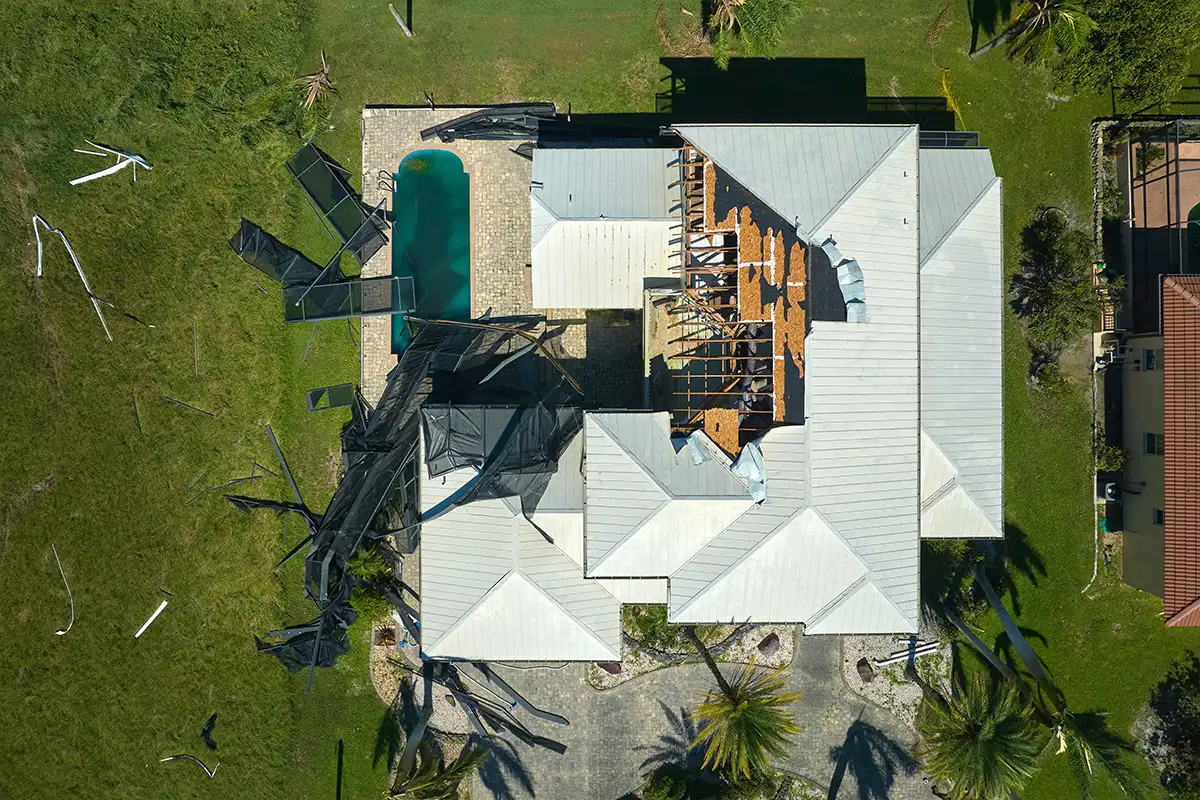
On March 10, 2026, hail nearly 5 inches across struck Darien, a short drive from Naperville. In 2025, State Farm paid more hail claims in this state than in almost any other, while winter ice masks cracked shingles and wood.

The usual carrier move is to accept storm damage, then fund a patch job or cut deep for roof age. Property insurance appraisal services give appraisers a Xactimate picture of the real cost, with matching, code upgrades, and hidden items counted.

Our Services

Support at Each Stage, From Written Demand to Final Award

Insurance claim appraisal fixes the dollar amount of a loss and leaves coverage for another day. That means your numbers must carry the case, and we build them from demand letter to award.
01

Dispute Type Review

First, we sort out whether the carrier is fighting the price or the coverage. We then read your appraisal clause, note each deadline, and confirm how the demand must be sent.
02

Xactimate Estimates for Appraisal

Your property damage estimate gets priced to its ZIP code and built one line at a time. Photos and notes sit behind waste, steep charges, matching, and code items like ice barrier.
03

Appraiser Support Services

Your appraiser walks into each meeting with an organized insurance appraisal report, a two-column comparison, and backup for every line under dispute, plus prep notes for defending the numbers.

04

Umpire Support Services

Deadlocked appraisers hand the open items to an umpire. We prepare a packet that shows each gap, the evidence behind your figure, and the reasoning an umpire needs to side with it.
05

Side-by-Side Estimate Comparison

Put the carrier’s Xactimate or Symbility numbers next to ours and the gaps jump out: quantities, unit costs, labor minimums, depreciation, and O&P (overhead and profit), all in one report.

06

Post-Award Payment File

A signed award still has to turn into a check. We package the itemized totals, agreed items, and recoverable depreciation into one tidy file, giving the carrier no reason to stall.
Estimators Who Have Prepared

Over 500 Appraisal and Umpire Files

Since Robert Russo launched Claim Guard in 2018, our insurance valuation services have followed one rule: every disputed dollar comes from physical proof and ZIP-code pricing, just like leading appraisal firms.

Already holding a Symbility or carrier estimate? We will measure it against your field numbers and flag each missing item.

HOW IT WORKS

Step-by-Step That Turns a Disputed Claim Into an Award

Our process follows four clear steps. Most files move from upload to delivery in about two business days, and your team never has to learn Xactimate or chase extra paperwork.
  1. 01

    Send the Dispute File

    Upload the carrier's estimate, the appraisal demand, photos, and measurements. Tell us exactly which line items are in dispute, so our review starts with the real gap in the numbers.

  2. 02

    We Audit the Gap

    An estimator compares both estimates line by line against local code and current ZIP-code pricing. Every disputed item gets a photo, a code note, or a pricing reference behind it.

  3. 03

    Your Appraisal File Arrives

    You receive an appraisal-ready Xactimate estimate, a comparison report, and a short summary of every disputed item. The file goes straight to your appointed appraiser, ready for the first meeting.

  4. 04

    Support Through the Award

    Full-service clients get revisions after appraiser meetings and umpire packets whenever they are needed. Once the award is signed, we organize the itemized totals so payment moves without new delays.

Which Documents Make

A Property Damage Appraisal Case Hard to Beat?

A property insurance appraisal is decided on proof, not promises. Anything appraisers and umpires cannot see or verify carries little weight, so collect the six items below before anyone sits down.
Because Xactimate updates its price lists often, every Claim Guard file uses the latest pricing for that property’s ZIP code.
Why Contractors Choose

Claim Guard for Every Insurance Appraisal

Storm season buries solo estimators fast, and appraisal clocks keep ticking. Our insurance appraisal services draw on roughly 25,000 estimates written since 2018, and each file passes through backup estimators and a final review.
Contractor Reviews

What Local Roofers and Adjusters Say About Our Appraisal Files

Estimating help only matters if it pays off. Roofers, contractors, and public adjusters from Chicago, Naperville, and Evanston share how our insurance appraisal services changed turnaround, appraisal results, and recovered money.
★★★★★
“

Claim Guard reviewed our estimate, found several missed line items, and prepared everything clearly. The entire process was organized, responsive, and easy to follow.

★★★★★
“

Their team saved us hours of paperwork and helped document the supplement correctly. Communication stayed clear from the first review through final submission.

★★★★★
“

The estimate was detailed, accurate, and delivered quickly. Claim Guard has become a reliable part of our claims process whenever a file needs closer review.
Who We Work With

The Firms That Rely on Our Appraisal Desk

Maybe you send three files a month. Maybe you send three hundred after one hailstorm. Either way, Claim Guard adjusts to your volume, and each insurance claim appraisal receives the same patient, line-by-line check.
01

Contractors

Restoration and general contractors call on our appraisal support when a roof leak turns into wet ceilings, soaked insulation, and ruined drywall. We scope each room, log drying equipment days, and price every trade to the ZIP code.
02

A carrier that admits storm damage but only funds a repair is the classic reason roofers choose appraisal. Our files prove discontinued shingles, matching issues, steep charges, and code items, making the case for a complete replacement.
03
During appraisal, public adjusters handle the heavy estimating work. We prepare the insurance appraisal report, the comparison between both estimates, and the umpire packet, leaving the licensed adjuster free to advocate for clients and run claims.
Gallery​

Recent Projects

150+ Contractors & PAs Served
25K+ Estimates Written
$30M+ Claim Increases Documented
500+ Appraisal & Umpire Files
48hr Typical Turnaround
Serve Area

Our Appraisal Service Area

Across Illinois

Claim Guard works from McHenry, northwest of Chicago, and delivers property insurance appraisal services remotely to contractors and public adjusters in Chicago, Naperville, and Evanston. Our team is available Monday through Friday, 9 AM to 5 PM, and prices every file by ZIP code.
Our Blogs

Field Notes on Getting More From Appraisal Disputes

Practical stories and tips on turning underpaid claims into paid ones, straight from our estimating and supplement desk.
Faqs

Common Insurance Appraisal Questions Explained

These are the questions that come up most when a roofer, contractor, or public adjuster weighs an appraisal.

how much does an insurance appraisal cost?

A home insurance appraisal typically runs a few thousand dollars per side. Each party covers its own appraiser under most homeowners policies, and the umpire fee is split in half. Smaller residential cases often cost $1,500 to $3,000 per appraiser.
Most insurance appraisal cases wrap up in a few weeks to several months. Standard homeowners policies allow 20 days for each side to name an appraiser and 15 more days to choose an umpire, and completed files move faster.
Appraisal awards generally bind both sides on the amount of loss, with exceptions for fraud, collusion, or an obvious mistake. Coverage disputes remain a matter for the courts, so policy defenses can still come up after the award is signed.
A policy defense alone does not let an insurer block appraisal. In Zhao v. State Farm (2024), a state appellate court ruled that issues such as late notice do not stop appraisal on the amount of loss.
Only three parties can negotiate an insurance claim: the policyholder, a licensed public adjuster, or an attorney. Roofers and contractors may document damage, write estimates, and supplement their own scope, but negotiating coverage for an owner is off limits.
Ready to Recover More?

Is Your Roof Claim Stuck in a Pricing Standoff?

Money lost on an underpaid claim is profit your crew already worked for. With Claim Guard, you gain seasoned estimators, 48-hour files, and storm-season backup, without paying for software, new salaries, or long training periods.
01

File Review

Your estimate, the carrier's figure, and your photos get compared until each contested dollar is clear.

02

Documentation Support

Every photo, measurement, and code note is arranged so appraisers and umpires can trace the numbers.

03

Estimating Assistance

Most appraisal-ready Xactimate files, priced to the local ZIP code, reach you within 48 hours.
Request Your Free Review

Tell us about your claim and our team will be in touch to schedule your free review.